CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 55% of retail CFD accounts lose money when trading CFDs with this provider. You should consider whether you understand how CFDs work, and whether you can afford to take the high risk of losing your money.
eToro is a multi-asset investment platform. The value of your investments may go up or down. Your capital is at risk.
Recommended for beginners
Stock brokers
252 customers chose this
Commission on US stocks$0
Minimum deposit$1
Number of stock exchanges10
Number of stocks10000
Number of ETFs3,000+
Inactivity fee$10 per month (free if account meets minimum activity)
Investing involves risk. Commission-free trading of stocks, ETFs and options refers to $0 commissions for Robinhood Financial self-directed individual cash or margin brokerage accounts that trade U.S. listed securities via mobile or web. Regulatory and exchange fees may apply. Please see Robinhood Financial Fee Schedule to learn more.
We can't guarantee the data is fully accurate every day.
Filters
Broker features
Deposit methods
Support channels
Product Statistics
A complete breakdown of all data points across the products in this comparison to help you make the right decision.
Currency exchange fee
0% - 1% (0.44%)
Minimum deposit
$0 - $75 ($18.86)
Demo account
4 (57.1%)
Interest on uninvested funds
6 (85.7%)
Robo Advisor
4 (57.1%)
Copy Trading
1 (14.3%)
Fractional shares
6 (85.7%)
Bank Transfer
1 (14.3%)
Debit Card
6 (85.7%)
Web
7 (100%)
iOS
7 (100%)
Android
7 (100%)
Desktop
6 (85.7%)
Mac
1 (14.3%)
Mobile App
1 (14.3%)
Live chat
6 (85.7%)
Email
7 (100%)
Phone
5 (71.4%)
24/7 Support
5 (71.4%)
Community forums
4 (57.1%)
Branch Access
1 (14.3%)
Statistics based on 7 Stock brokers products in our database.
Financer's Choice
Top Rated
TradeStation
$0 commissions on stocks and ETFs. Options at $0.60 per contract with volume discounts. No account minimum. The $10/month inactivity fee and $125 ACAT transfer fee are higher than competitors.
Support available via phone, email, and live chat. Response times are generally prompt, though some users report mixed experiences with complex technical issues on the platform.
Clear pricing tiers for active traders. SEC, FINRA, and NFA regulated. The $125 transfer-out fee and $50 IRA closure fee reduce flexibility. Margin requires $2,000 minimum balance.
The new TITAN X platform is well-received by active traders for its advanced charting and customizable workspaces. The mobile app and web platform lag behind the desktop experience.
Get exclusive terms from the best financial companies
What Is Annual Percentage Yield (APY)?
Annual Percentage Yield (APY) is the real rate of return you earn on a savings account, certificate of deposit (CD), or other interest-bearing account over one year. Unlike a simple interest rate, APY includes the effect of compound interest, which means you earn interest on the interest you've already accumulated.
Banks are required by federal law (the Truth in Savings Act) to disclose APY, making it the most reliable number for comparing savings products apples-to-apples.
Here's a quick example: if you deposit $10,000 into a savings account with a 4% interest rate compounded daily, the APY comes out to about 4.08%. After one year, you'd have $10,408, not just $10,400. That extra $8 comes from compound interest working in your favor.
How to Calculate APY
The APY formula accounts for both the nominal interest rate and how often interest compounds:
APY = (1 + r/n)^n - 1
Where:
r = the nominal annual interest rate (as a decimal)
n = the number of compounding periods per year
Let's say a savings account offers 4% interest compounded monthly:
r = 0.04
n = 12
APY = (1 + 0.04/12)^12 - 1 = 0.0407 = 4.07%
If that same 4% compounds daily (n = 365):
APY = (1 + 0.04/365)^365 - 1 = 0.0408 = 4.08%
The more frequently interest compounds, the higher the APY. That's why daily compounding beats monthly, and monthly beats quarterly.
Compounding Frequency
Periods Per Year (n)
APY on 4% Rate
Earnings on $10,000
Annual
1
4.00%
$400.00
Quarterly
4
4.06%
$406.04
Monthly
12
4.07%
$407.42
Daily
365
4.08%
$408.08
What Is a Good APY?
A "good" APY depends on the type of account and current market conditions. As of 2026, the national average savings account APY is just 0.39% according to the FDIC. But the best high-yield savings accounts offer rates up to 5.00% APY, more than 12 times the average.
Here's a general benchmark for what constitutes a competitive APY across different account types:
High-yield savings accounts: 4.00% to 5.00% APY
Money market accounts: 3.50% to 4.50% APY
1-year CDs: Up to 4.10% APY
Traditional savings accounts: 0.01% to 0.60% APY
APY rates are closely tied to the Federal Reserve's federal funds rate. When the Fed raises rates, APYs on savings products tend to rise. When the Fed cuts rates, APYs follow. The current federal funds rate sits at 3.50% to 3.75% after several cuts in late 2025.
Variable APY vs. Fixed APY
There are two types of APY you'll encounter when shopping for savings products, and the difference matters for your financial planning.
Variable APY fluctuates based on market conditions and the Federal Reserve's interest rate decisions. Most savings accounts and money market accounts offer variable APYs. When the Fed cuts rates, your APY may drop. When rates rise, your APY can increase. This is the most common type.
Fixed APY stays the same for a set period, regardless of what happens to market rates. CDs are the most common product with fixed APYs. If you lock in a 1-year CD at 4.10% APY today, you earn that rate for the full term, even if the Fed cuts rates tomorrow.
The trade-off is straightforward: variable APYs give you flexibility (you can withdraw anytime), while fixed APYs give you certainty (your rate won't drop, but you may face early withdrawal penalties).
Feature
Variable APY
Fixed APY
Rate changes?
Yes, based on market conditions
No, locked for the term
Common products
Savings accounts, money markets
CDs, some bonds
Withdrawal flexibility
Withdraw anytime
Early withdrawal penalties
Best when rates are
Rising (you benefit from increases)
Falling (you're locked in higher)
Risk
APY may drop if Fed cuts rates
You miss out if rates rise
APY vs. Interest Rate: What's the Difference?
The nominal interest rate is the basic percentage a bank pays on your deposit. APY takes that rate and factors in compounding, showing you the actual amount you'll earn over a year.
Think of it this way: the interest rate is the advertised speed, while APY is the actual distance you'll travel. They're closely related, but APY is always equal to or higher than the interest rate (assuming compounding happens more than once a year).
For practical purposes, if two banks both advertise a 4% interest rate but one compounds daily and the other compounds annually, the daily-compounding bank gives you a higher APY (4.08% vs. 4.00%). That's why APY is the better number to compare.
Banks are legally required to publish APY under the Truth in Savings Act, specifically so consumers can make fair comparisons.
APY vs. APR: Know the Difference
APY and APR look similar but serve opposite purposes:
APY (Annual Percentage Yield) = what you earn on savings and investments
APR (Annual Percentage Rate) = what you pay on loans and credit cards
APR includes the interest rate plus any fees charged by the lender (origination fees, closing costs, etc.). APY includes the base interest rate plus the effect of compounding.
Here's where it gets practical: when you're saving money, you want the highest APY possible. When you're borrowing money, you want the lowest APR possible.
A credit card with a 24% APR costs you roughly 2% per month on your outstanding balance. A savings account with a 4.50% APY earns you about 0.37% per month on your total balance, including previously earned interest.
APY
APR
Measures
What you earn
What you pay
Includes
Interest rate + compounding
Interest rate + fees
Used for
Savings accounts, CDs, money markets
Loans, credit cards, mortgages
Goal
Higher is better
Lower is better
Compounding
Included in calculation
Not typically included
How APY Affects Your Savings Over Time
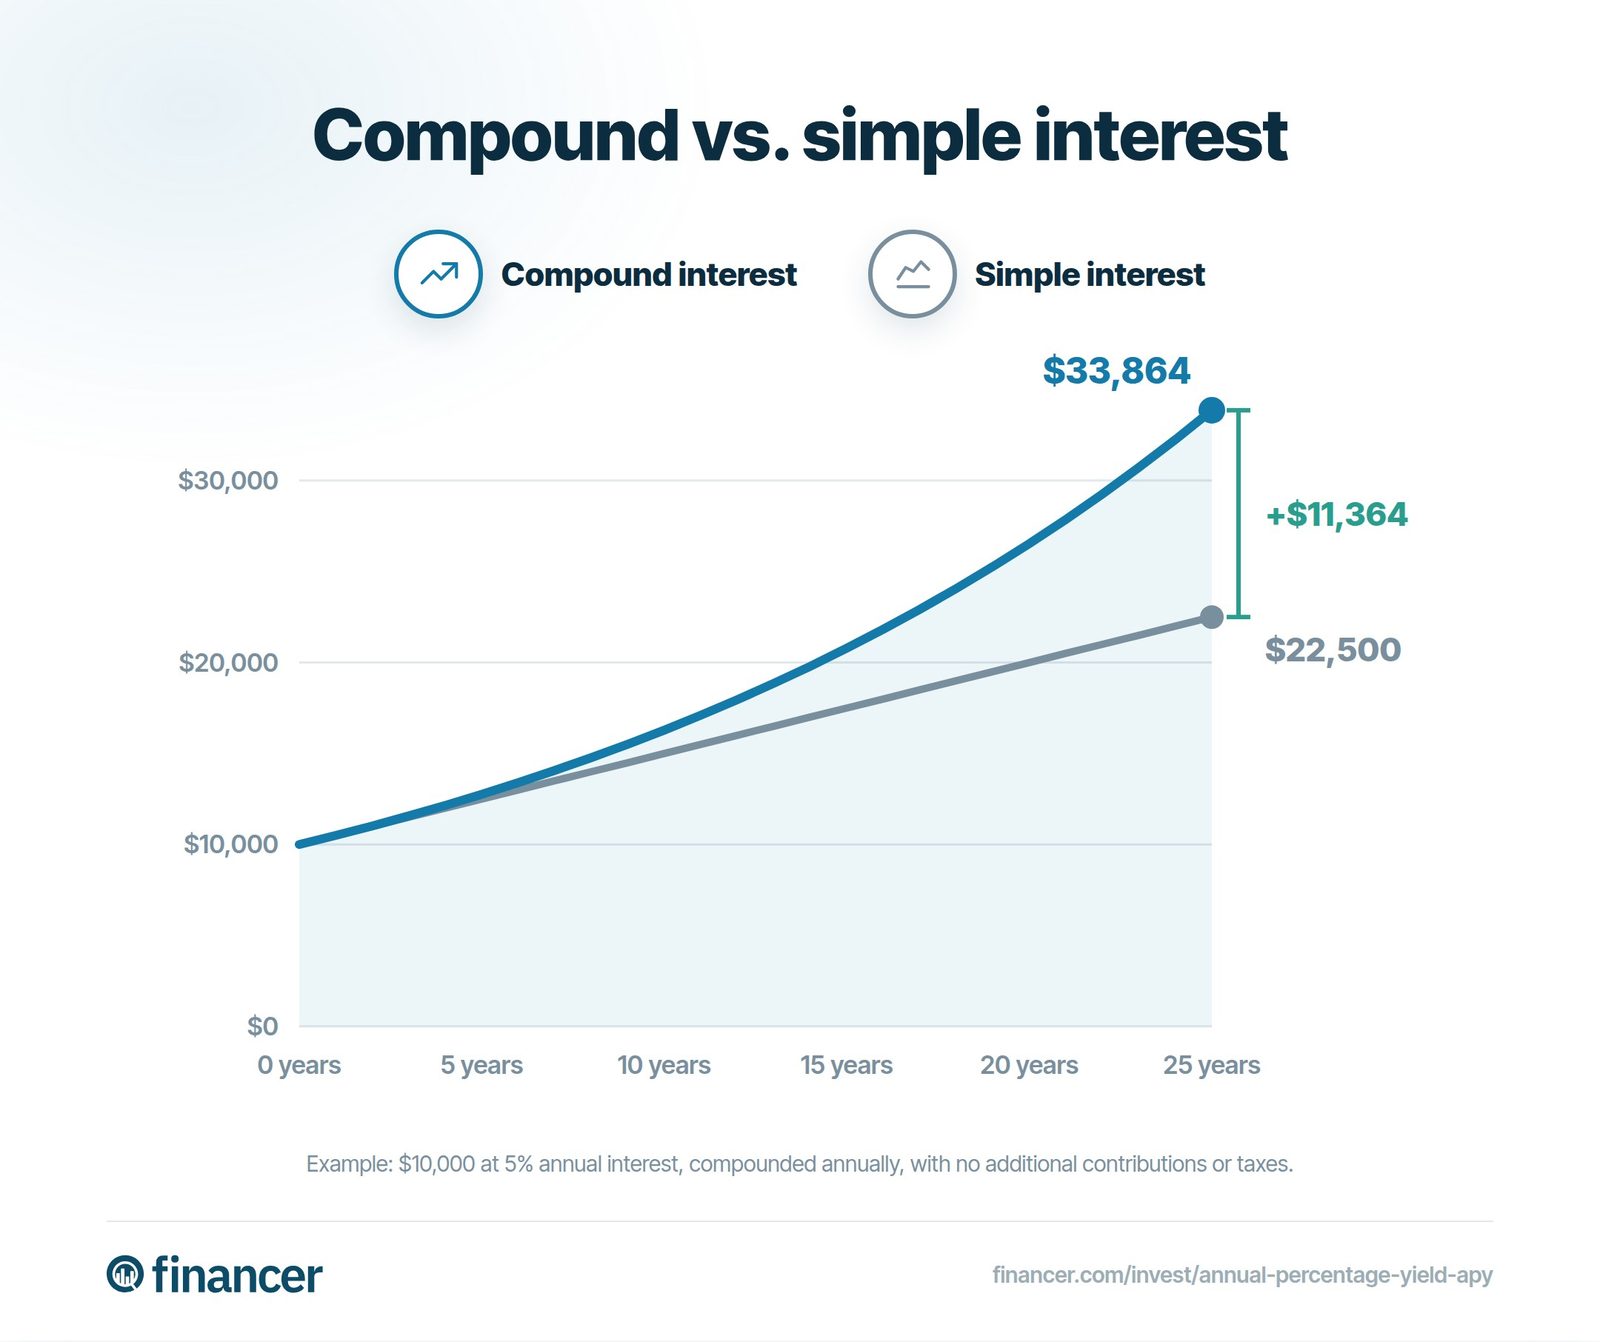
The real power of APY shows up over longer time horizons. Compound interest creates a snowball effect where your earnings accelerate year after year.
Consider a $10,000 deposit at 4.50% APY:
After 1 year: $10,450
After 5 years: $12,462
After 10 years: $15,530
After 20 years: $24,117
That same $10,000 at the national average of 0.39% APY would only grow to $10,039 after year one, and just $10,808 after 20 years. The difference between a high-yield account and a traditional savings account over two decades is $13,309 in pure interest earnings.
You can run your own numbers with our compound interest calculator to see how different APYs affect your specific savings goals.
Where to Find the Best APY Rates
The biggest APY gap is between traditional banks and online banks. Brick-and-mortar banks often offer APYs under 0.10% on savings accounts because they have high overhead costs (branches, staff, real estate). Online banks, credit unions, and fintech companies consistently offer the highest APYs because they operate with lower costs.
Here's where to look:
Online high-yield savings accounts offer the best combination of high APY and easy access to your money. Many have no minimum balance requirements and no monthly fees.
Certificates of Deposit (CDs) lock your money for a set term (3 months to 5 years) in exchange for a guaranteed fixed APY. Longer terms often pay higher rates.
Money market accounts combine higher APYs with check-writing and debit card access, though they may require higher minimum balances.
Before opening any account, verify that the institution is FDIC-insured (banks) or NCUA-insured (credit unions). Compare APYs, minimum balance requirements, fees, and withdrawal limits.
Is APY Paid Monthly or Yearly?
APY is an annual rate, but most banks actually pay interest monthly. Here's how it works: the bank divides your APY into 12 monthly portions and credits your account each month.
For example, with a 4.50% APY on $10,000, you won't receive $450 at the end of the year in one lump sum. Instead, you'll receive roughly $36.70 in the first month (slightly less than 1/12 of the annual total because compounding builds gradually). Each subsequent month, you earn interest on a slightly larger balance.
Some banks compound daily but credit monthly. Others compound and credit monthly. The frequency of crediting doesn't change your APY, it just changes when you see the money appear in your account.
Compare savings accounts to find accounts with the APY and payout schedule that works for your savings strategy.
Frequently Asked Questions
What is APY and how does it work?
APY stands for Annual Percentage Yield. It measures the total interest you earn on a deposit or savings account over one year, including the effect of compound interest. Unlike a simple interest rate, APY accounts for how often your interest compounds (daily, monthly, quarterly), giving you an accurate picture of your real earnings.
How is APY calculated?
APY is calculated using this formula: APY = (1 + r/n)^n - 1, where r is the nominal annual interest rate and n is the number of compounding periods per year. For example, a 4% interest rate compounded daily (365 times per year) gives an APY of 4.08%.
What is a good APY on a savings account?
A good APY depends on current market conditions. As of 2026, the national average savings account APY is 0.39%, but the best high-yield savings accounts offer 4.00% to 5.00% APY. Any rate significantly above the national average is considered good. Online banks and credit unions typically offer the highest APYs.
What is the difference between APY and APR?
APY measures what you earn on savings and investments, while APR measures what you pay on loans and credit. APY factors in compound interest on your earnings. APR includes the interest rate plus lender fees on borrowed money. When saving, look for a high APY. When borrowing, look for a low APR.
Is APY paid out monthly?
APY is an annual rate, but most banks pay interest monthly. The bank divides your annual yield into monthly portions and credits your account each month. Compounding means each month's interest payment slightly increases, because you're earning interest on previously earned interest.
Does a higher APY mean more risk?
Not necessarily. As long as your money is in an FDIC-insured bank or NCUA-insured credit union, your deposits are protected up to $250,000 per depositor, per institution. Online banks often offer higher APYs because they have lower overhead costs, not because they're riskier.